
Tutustu Huittisten kirjanpidon ja palkanlaskennan asiantuntijoihin
Monipuolista taloushallinnon osaamista, pitkiä asiakassuhteita ja henkilökohtaista palvelua. Huittisten tiimin erityisvahvuuksiin kuuluu...
The guidelines for Income taxation of non-resident foreign corporate entities have been updated regarding remote work when evaluating the formation of a permanent establishment.

In remote work arrangements, work can be done partly at home, and partly in the office located in the foreign company’s country of residence, or elsewhere.
When evaluating the formation of a permanent establishment, employee’s work duties in its entirety, the relationship of the work done at home to the other activities of the company, and to the work done outside home office, are considered.
Only carrying out activities considered to be other than assisting and preparatory work from the employee’s home, can constitute a permanent establishment in Finland for a foreign company.
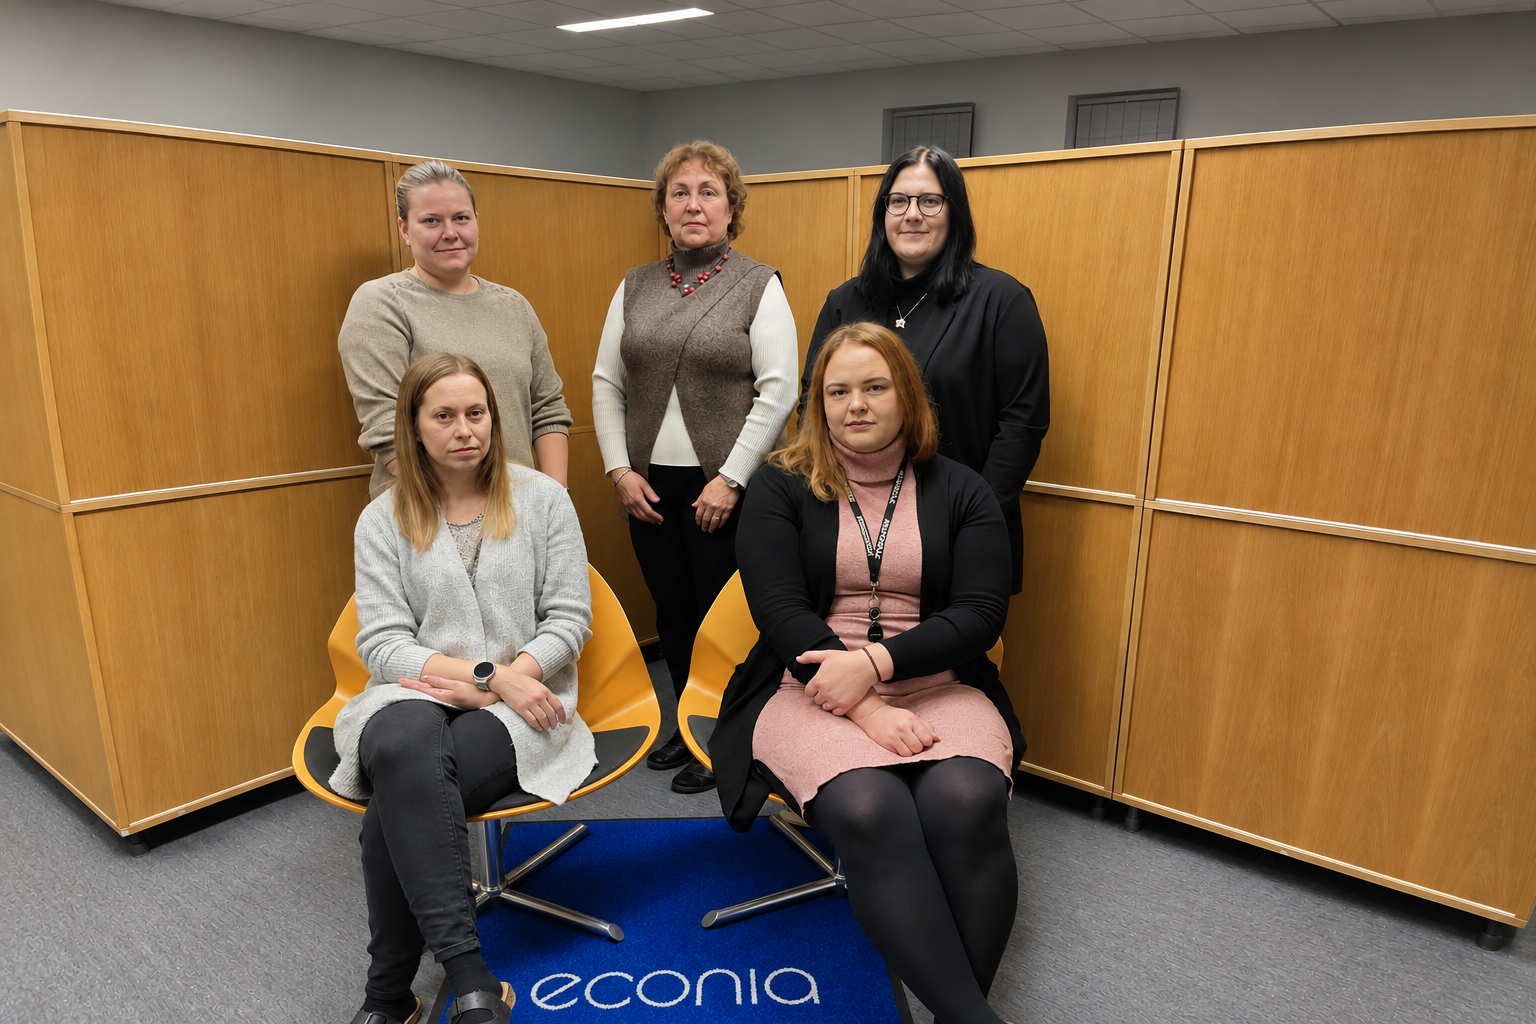
Monipuolista taloushallinnon osaamista, pitkiä asiakassuhteita ja henkilökohtaista palvelua. Huittisten tiimin erityisvahvuuksiin kuuluu...

Joulu lähestyy ja monet yritykset haluavat ilahduttaa henkilöstöään ja yhteistyökumppaneitaan lahjoilla tai järjestämällä pikkujouluja. Jotta joulun...
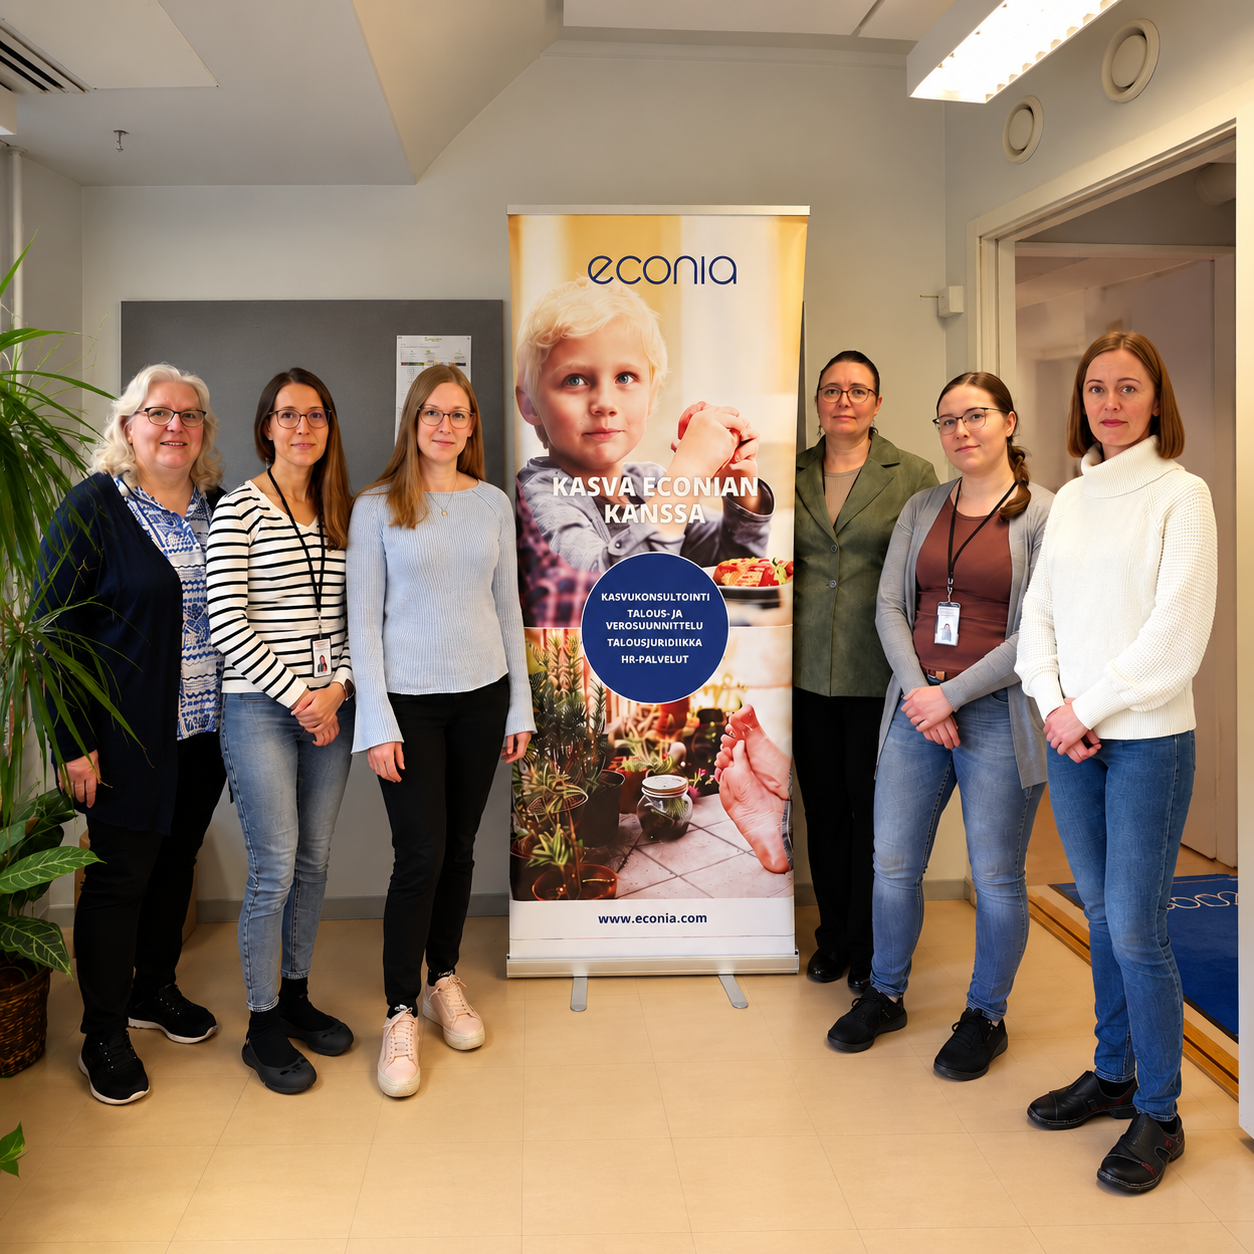
Pitkä kokemus, sähköisen taloushallinnon edelläkävijyys ja henkilökohtainen palvelu. Itsenäisyydenkadun toimistolla Tampereen keskustassa...